Diminished Value After Repairs
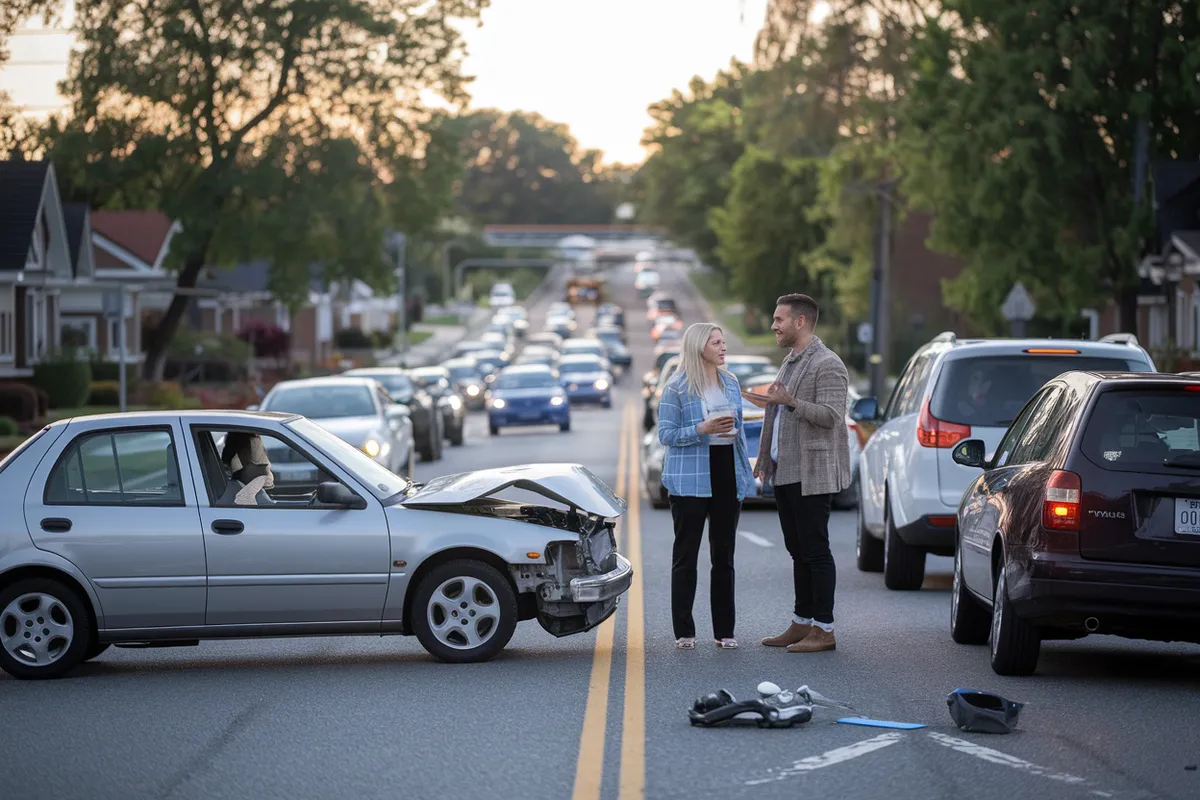
Diminished value refers to the difference between what a repaired vehicle would sell for before an incident and what it sells for after repairs, even if the work returns the car to a safe, functional condition. The key point is that the loss is about market perception and resale pricing, not about whether the repair meets mechanical standards.
Recoverability depends on the legal and factual context. Some jurisdictions treat diminished value as a recoverable element of damages in certain circumstances, while others limit recovery or require proof that the loss is measurable. Insurance practices also vary: some carriers pay only for repair costs, while others consider diminished value when documentation supports a specific market impact.
Practical examples help. A late-model sedan with a clean history may sell for less after a collision because buyers discount the “repaired” label, even when parts are replaced and paint matches. A minor bumper repair can still affect pricing, but the magnitude often depends on repair scope, whether the vehicle is branded, and how the market views the incident.
Evidence matters because diminished value claims are not based on feelings. They rely on comparable sales, repair records, and a credible explanation of why the market would price the vehicle lower. That explanation often includes the repair extent, the absence or presence of structural damage, and the vehicle’s pre-incident condition.
Common Mistakes And Dependencies
People often assume that “repaired correctly” automatically means “no diminished value.” Market pricing can still drop because buyers factor in risk, inconvenience, and the fact that a vehicle has an incident history. A repair shop’s quality does not erase the buyer’s discount behavior.
Another frequent error is mixing up diminished value with other claim categories. Repair cost reimbursement covers parts, labor, towing, rental, and related expenses. Diminished value targets the resale price gap, which requires separate proof and a different measurement approach.
Claims also depend on supporting technologies and data sources. Repair documentation typically comes from estimates and invoices generated by estimating systems used by insurers and shops. Comparable sales data may come from vehicle listing databases, auction results, or valuation services that track transaction prices. When a claim relies on a valuation report, the methodology and inputs become the battleground—especially if the report uses broad assumptions or outdated comparables.
Branding and title status can change everything. If a vehicle receives a salvage or rebuilt brand, the market discount tends to be larger and more obvious. If the title remains clean, diminished value may still exist, but the proof usually has to be tighter because the market impact can be smaller and more disputed.
Timing affects evidence quality. A resale listing posted weeks after repairs may reflect early buyer skepticism, while later sales may show different pricing once the incident becomes “old news.” That is why claim files often include a timeline of repairs, inspections, and sale or listing activity.
How To Build A Recoverable Claim
Document Repairs With Precision
Start with a repair packet that includes the insurer or shop estimate, the final invoice, photos before and after repair, and the parts list showing what was replaced versus refinished. Keep the vehicle identification number (VIN) consistent across documents. If you have a supplement or change order, include it because it can explain why the final repair scope differs from the initial estimate.
For a practical aside: many shops generate photos through their own workflow, and the file names sometimes omit the date. If you see missing timestamps, add a short written timeline yourself so the packet stays coherent for review. I have seen claims stall over missing “before” photos, which is frustrating because the mechanical repair may be fine.
Also record any structural inspection results. If the incident involved airbags, frame components, or alignment work, the repair packet should state what was checked and what was adjusted. Structural work often correlates with larger market discounts, but it also increases the need for clear documentation.
Use Market Evidence, Not Assumptions
Diminished value claims usually require a market-based comparison. That can mean a before/after valuation using comparable sales, or a report that estimates the resale price difference attributable to the incident history. The best reports explain the comparable selection criteria, such as model year, trim, mileage band, geographic area, and whether the comparables have incident histories.
Be cautious with reports that rely on generic averages. If a valuation tool uses a “typical” discount without tying it to your vehicle’s repair scope, it may not survive scrutiny. Some valuation services also update their models; a report dated 2023 may not match market behavior in 2024, and the date can matter when the claim is reviewed.
If you plan to sell the vehicle, consider capturing listing data. A short record of comparable listings for similar clean-history vehicles versus your repaired vehicle can support the narrative, but it should not replace a formal valuation if the insurer demands one.
Match The Legal Theory To The Facts
Recoverability depends on the applicable law and the incident facts. Many states allow some form of diminished value recovery, but the rules vary on whether recovery is limited to certain circumstances, such as total loss versus partial loss, or whether the claim must be proven with “reasonable certainty.” Some jurisdictions also treat diminished value differently depending on whether the repair restored the vehicle to pre-accident condition.
Because laws differ, treat legal guidance as jurisdiction-specific. If you are in the U.S., your state’s statutes and case law control, and the insurer’s policy language can also affect claim handling. If you are outside the U.S., the governing law may follow different standards for damages and proof.
When you submit a claim, connect the evidence to the theory. If the theory requires measurable market loss, your packet should include valuation methodology and repair scope. If the theory focuses on the difference in market value, your comparables should be close in time and location.
Negotiate With A Clear Demand Package
Insurers often respond faster when the demand package is organized and consistent. Include a one-page summary with the incident date, repair completion date, and the claimed diminished value amount. Attach the repair packet, the valuation or comparable sales analysis, and any communications showing the insurer’s position.
For a small but practical detail: label attachments with dates and short descriptions, such as “Repair Invoice 2026-03-14” or “Before Photos 2026-03-02.” Reviewers handle many files, and clear naming reduces back-and-forth.
Set realistic expectations. Diminished value amounts can be modest for minor repairs and larger for incidents that affect structural components, airbags, or paint quality. If your repair scope is limited to a bumper cover with no paint mismatch and no structural involvement, the insurer may argue the market impact is minimal.
Educational Case Examples
Clean Title, Minor Collision
A 2019 hatchback with 35,000 miles suffered a left-rear bumper impact. The owner obtained a repair invoice showing replacement of the bumper cover and repainting, with no airbag deployment and no frame work. The title remained clean, and the owner kept the full photo set from the shop.
For the diminished value claim, the owner used a valuation report that compared the vehicle to similar clean-history listings within a narrow mileage band. The report estimated a resale gap of a few hundred dollars, reflecting a smaller market discount for a non-structural repair. The insurer initially denied, citing repair quality, but the owner’s market-based comparables shifted the outcome because the report tied the discount to incident history rather than mechanical defects.
Airbag Deployment After Repair
A 2021 sedan experienced a front-end collision with airbag deployment. Repairs included replacement of airbag components and alignment checks, with documented calibration steps. The owner’s packet included the final invoice, parts list, and a statement from the shop describing what was inspected and calibrated.
The diminished value analysis used comparables that matched trim and mileage and excluded vehicles with salvage branding. The estimated loss was higher than in the minor collision scenario because the market tends to discount vehicles with deployed airbags, even when repairs are performed correctly. The insurer’s counterargument focused on whether the vehicle was restored to pre-incident condition, so the owner emphasized the repair scope documentation and the market evidence showing a consistent resale gap.
Decision Checklist For Recoverability
| Question To Ask | What Helps | What Weakens The Claim | Your Next Step |
|---|---|---|---|
| Is the title branded? | Clear documentation of title status and repair classification | Unclear branding history or missing DMV paperwork | Pull the title/DMV record and include it in the packet |
| What was repaired? | Invoice, parts list, and photos showing scope and whether structural work occurred | Only a summary estimate with no final invoice or photo trail | Request a complete repair packet from the shop |
| How is the loss measured? | Comparable sales or valuation tied to your vehicle’s specifics | Generic “typical” discounts without comparable selection logic | Ask for the methodology and comparable criteria in writing |
| Does the claim match the law? | A theory of damages consistent with your jurisdiction’s standards | A demand that ignores jurisdiction limits or proof requirements | Check local rules or consult a qualified attorney for the jurisdiction |
Step-by-step checklist you can follow before submitting: gather the repair packet, confirm title status, identify the repair scope category (non-structural, structural, airbag-related), select valuation evidence with documented comparables, draft a demand summary that ties evidence to the claimed amount, and keep a timeline of communications.
Common Mistakes That Derail Claims
One mistake is relying on repair quality arguments alone. A shop’s workmanship matters for safety and function, but diminished value focuses on resale pricing after an incident history. If your submission lacks market evidence, the insurer may treat the claim as speculative.
Another mistake is using mismatched comparables. If the comparables differ in mileage, trim, options, or geographic market, the valuation can drift. A report that compares your vehicle to listings far away or with different equipment can look weak because buyers in your area may discount differently.
People also overstate the incident scope. If the repair invoice shows no structural work, but the claim narrative implies frame damage, the insurer may deny based on inconsistency. Keep the narrative aligned with the invoice and photos.
Some owners wait too long to gather evidence. If you sell the vehicle before you compile repair documents and valuation support, you may lose the chance to show the resale gap attributable to the incident. Even if you can still claim, the proof becomes harder.
Finally, avoid “one number” demands without a supporting explanation. A demand letter that states an amount with no measurement method often triggers a denial or a request for more documentation, which delays resolution.
FAQ
Can I claim diminished value if the car is repaired to factory specs?
Yes in some cases, because diminished value targets resale price impact from incident history, not only mechanical condition. Proof usually needs market-based evidence tied to your repair scope and title status.
What documents do insurers typically ask for?
Common requests include the repair estimate and final invoice, photos of damage and repairs, parts lists, proof of title status, and a valuation or comparable sales analysis showing the resale price difference.
How do I measure the lost worth of a repaired vehicle?
Most claims use comparable sales or a valuation report that explains comparable selection criteria such as mileage, trim, location, and incident history. The report should state its methodology and assumptions.
Does diminished value apply to minor bumper repairs?
It can, but the amount is often smaller and more disputed when the repair is non-structural and the title stays clean. Strong documentation and close comparables matter more for minor incidents.
Will a branded title change the claim?
Yes. Salvage or rebuilt branding usually creates a larger and more obvious market discount. Clean-title cases can still qualify, but they require tighter proof of measurable resale impact.
Author's Insight
Diminished value claims sit at the intersection of repair documentation and market pricing behavior. The strongest files treat the claim as a damages measurement problem: repair scope is documented, and the resale impact is supported by comparables or a valuation method with transparent inputs.
Because rules vary by jurisdiction and insurer practice, the same repair can lead to different outcomes. A careful approach focuses on evidence quality, consistent timelines, and a demand package that matches the legal standard for proof.
When evidence is thin, the claim often fails even if the repair work was done correctly. When evidence is specific, the dispute shifts from “the car is fixed” to “the market price moved by this amount, for these reasons.”
Key Takeaways
- Diminished value measures resale price impact from an incident history, not only whether repairs restore function.
- Recoverability depends on jurisdiction rules and proof standards, so align your claim theory with local requirements.
- Use a repair packet plus market evidence such as comparable sales or a valuation report with documented methodology.
- Title branding, repair scope (non-structural versus structural), and airbag involvement often drive the size of the market discount.
- A clear, organized demand package reduces delays and helps the review focus on measurable loss.