Claim Evidence Protocols
Insurance claim documentation comprises all the materials that prove a loss or damage occurred as per policy coverage. This can range from photographs, repair estimates, medical reports, police reports, receipts, and witness statements.
For example, in an auto insurance claim, evidence collection involves documenting vehicle damages with high-resolution images from multiple angles, gathering a police accident report, and keeping detailed repair invoices. According to the Insurance Information Institute (III), claims lacking proper documentation have a 40% higher chance of delays or denials.
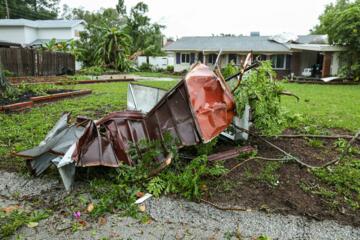
In property insurance claims, evidence should include dated photos, videos, and professional damage assessments. These documents create a timeline and validate the claim event, preventing fraudulent or inflated claims.
Common Evidence Problems
Insufficient or Incomplete Evidence
A prevalent issue is submitting incomplete evidence, such as unclear photos, missing police reports, or absent medical evaluations. This forces insurance companies to request follow-up information, delaying the claim process.
Lack of Organization
Disorganized files and inconsistent data hinder claim reviews. Missing receipts or mismatched dates reduce the credibility of the claim.
Ignoring Policy Requirements
Many claimants overlook specific documentation guidelines in their insurance policies, leading to rejected claims or reduced payout amounts.
Consequences
The consequences can include claim denials, prolonged settlement periods, or receiving lower compensation than deserved. For instance, a 2022 report by J.D. Power revealed that claims with poorly documented evidence took on average 23 days longer to resolve than well-documented claims.
Best Evidence Practices
1. Follow the Insurer's Documentation Checklist
What to do: Obtain and strictly adhere to the insurer’s claim documentation checklist, which typically specifies required evidence and submission formats.
Why it works: Aligns your documentation with insurer expectations, minimizing back-and-forth requests.
In practice: For example, Allstate Insurance provides accessible claim checklists via its website and mobile app, guiding customers through the evidence submission process efficiently.
2. Use Technology for Accurate Documentation
What to do: Utilize smartphones with high-resolution cameras and specialized apps like Claim Wizard or Snapsheet for photo documentation and claim tracking.
Why it works: These tools timestamp images, organize information, and upload documents directly to claim portals, reducing errors.
In practice: Snapsheet’s virtual claims management platform reports a 30% reduction in claim cycle time due to improved evidence collection.
3. Engage Professionals Early
What to do: Hire independent adjusters, contractors, or medical experts promptly after the incident to prepare impartial damage assessments and reports.
Why it works: Third-party validations enhance credibility and offer precise valuations.
In practice: Companies like Pilot Catastrophe Services specialize in on-site inspections and detailed reporting, which have helped reduce claim disputes by 25% for insurers using their services.
4. Keep Detailed Records and Create a Timeline
What to do: Document every interaction, payment, and update related to the claim, maintaining chronological order.
Why it works: Establishes a clear narrative for the claim and supports compliance with policy terms.
In practice: Microsoft OneNote and Google Docs can serve as effective tools for compiling this timeline, ensuring accessibility and searchability.
5. Submit Originals and Keep Copies
What to do: Whenever possible, provide original documents and make multiple copies stored physically and digitally.
Why it works: Originals are often necessary for validation; having copies prevents loss and speeds query resolution.
In practice: Using cloud storage platforms like Dropbox or Google Drive offers secure backup and easy sharing with claims handlers.
Claim Case Studies
Case Study 1: Auto Insurance Claim with Progressive
Company: John’s auto insurer, Progressive
Problem: After a collision, John’s initial claim was delayed due to blurry photos and missing the police report.
Solution: John used Progressive’s mobile app to retake high-quality images and submitted the police report digitally within 24 hours.
Result: The claim was processed 20% faster than average, and John received a settlement covering full repair costs.
Case Study 2: Home Insurance Claim with State Farm
Company: Anne’s insurer, State Farm
Problem: Anne experienced fire damage but failed to provide an independent damage assessment initially.
Solution: She enlisted a licensed professional through Pilot Catastrophe Services to conduct a comprehensive damage report.
Result: State Farm approved the claim with a payout 15% higher than their first estimate, as the professional report revealed additional structural damages.
Evidence Checklist
| Step / Goal | Action & Details | Recommended Tools |
|---|---|---|
| 1. Review | Study insurer’s checklist to understand requirements. | Insurer portal / App |
| 2. Photos | Document damages from multiple angles with timestamps. | Snapsheet / Camera |
| 3. Reports | Obtain official police or medical certified copies. | Police / Medical |
| 4. Experts | Get professional assessments for accurate valuation. | Pilot Catastrophe |
| 5. Receipts | Save all invoices and bills for compensation. | Cloud Storage |
Common Mistakes to Avoid
Inadequate Photographic Evidence
Low-quality or insufficient photos fail to clearly represent damages, resulting in underestimated claims.
Missing Official Reports
Absence of police reports or medical documentation delays claims and raises suspicion about the legitimacy.
Ignoring Deadlines
Late submission of documents contravenes policy terms and can lead to denial of claims.
Poor Organization
Submitting scattered documents without clear order complicates insurer review and lengthens claim duration.
How to Avoid:
- Use apps with automatic timestamps for photos
- Request reports immediately after incidents
- Keep a checklist and calendar reminders
- Organize documents in labeled folders, digital and physical
FAQ
What are the essential documents for filing an insurance claim?
Essential documents typically include proof of loss such as photos, police reports, medical reports, repair estimates, receipts, and correspondence with the insurer. Requirements may vary based on claim type and policy.
How soon should I collect evidence after an incident?
Collect evidence immediately or as soon as it is safe to do so. Early documentation ensures accurate capture of damage conditions and supports timely claim filing.
Can I submit digital copies of documents for my claim?
Most insurers accept digital submissions through apps or portals. However, some may require certified or original documents depending on the nature of the claim.
What role do professional assessors play in evidence collection?
Professional assessors provide unbiased damage evaluations that validate the extent of loss, helping insurers determine fair settlements and reducing disputes.
How can I prevent claim processing delays?
Follow the insurer’s checklist precisely, provide high-quality evidence, meet submission deadlines, keep organized records, and respond swiftly to requests for additional information.
Author's Insight
With over a decade of experience in insurance operations, I have witnessed firsthand how meticulous documentation transforms claim outcomes. Many clients underestimate the power of early, high-quality evidence collection. I recommend leveraging insurer apps and expert assessors to build an ironclad claim. Practical organization — such as maintaining a digital timeline — not only speeds up settlements but also prevents unnecessary stress. In my view, investing time in documentation upfront saves valuable time and money down the line, ensuring both policyholders and insurers benefit fairly.
Summary
Effective insurance claim documentation relies on clear, comprehensive, and organized evidence collection. Use insurer-specific checklists, digital tools like Snapsheet, professional assessments, and maintain thorough records to avoid delays and maximize settlements. By addressing common pitfalls and following structured protocols, claimants can significantly improve claim success rates and foster trust with insurers.